








Newsletter Subscribe
Enter your email address below and subscribe to our newsletter

Enter your email address below and subscribe to our newsletter
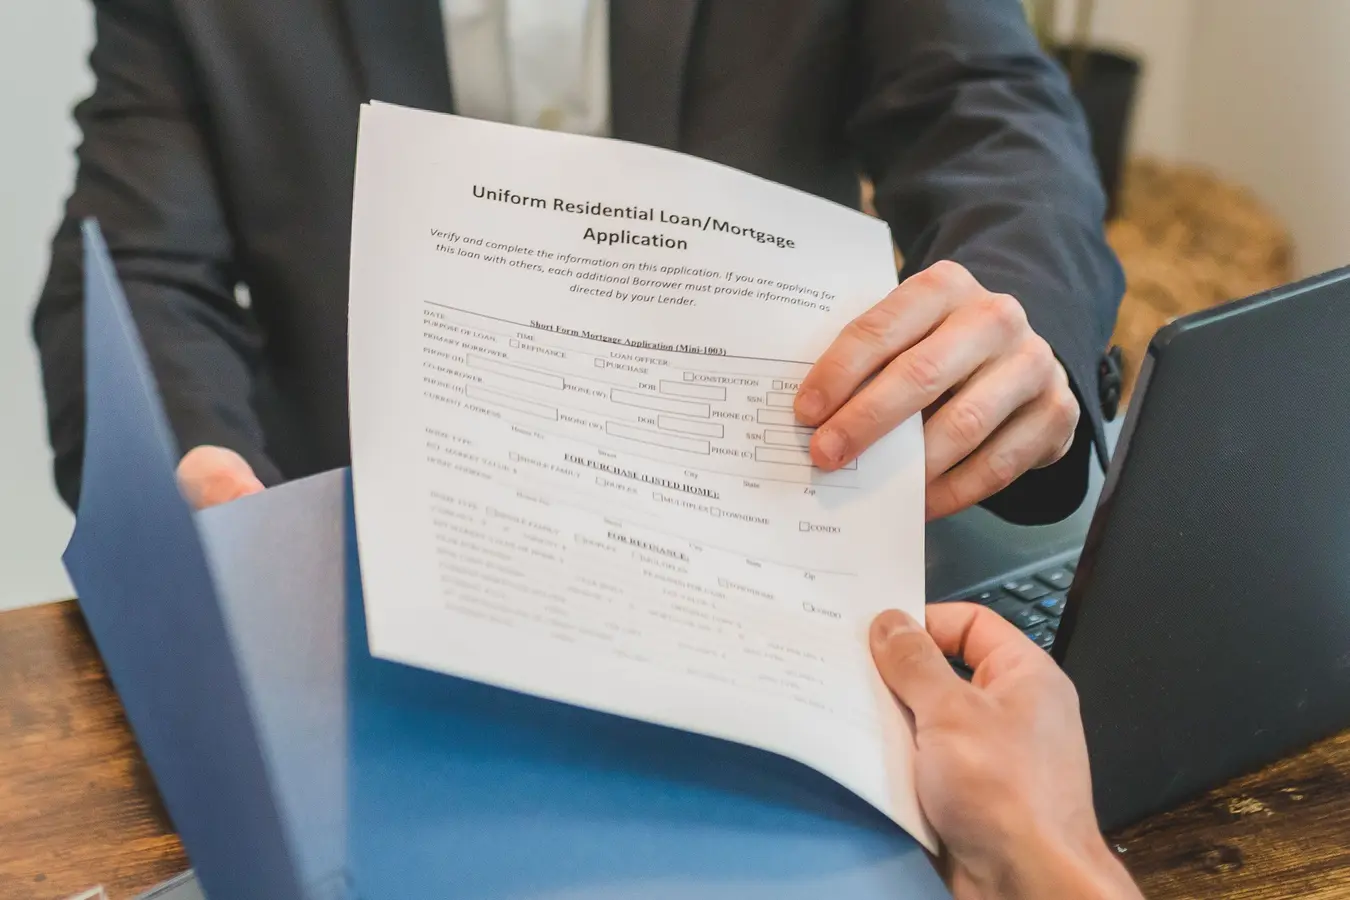
Many homebuyers start with one number: the advertised rate. Then the real questions show up. Is that rate fixed or only fixed for a short period? How much will the monthly payment become after repricing? Will fees, insurance, and loan term change the total cost more than expected?
If you are checking mortgage loan interest rates PNB offers, it helps to look at the quote the way a careful borrower would, not just the way a promo ad presents it. The rate matters, but so do the repayment period, the type of property, your income profile, and the charges wrapped into the loan process.
This guide breaks down what usually affects a PNB mortgage rate, how to compare options without getting lost in the details, and what to check before you commit. The goal is simple: understand what you may actually pay, not just what appears in the headline figure.
There is no single mortgage rate that applies to every borrower. Banks price home loans based on a mix of market conditions and borrower-specific risk. That means the rate one applicant gets from PNB may not be exactly the same as the rate another borrower sees, even if both are buying similar properties.
Part of that pricing starts outside the bank. Mortgage rates generally move with broader interest rate conditions and the bank’s own funding costs. When market benchmarks rise, housing loan offers often follow. When they ease, new loan offers may become more competitive. But market movement is only part of the picture.
Your actual offer can also change based on:
That is why comparing only one posted rate can be misleading. A low advertised figure may apply to a short fixed term, a certain borrower profile, or a limited promo. What matters more is whether that rate fits your repayment timeline and whether the bank’s assumptions match your application.
Before getting attached to a number, confirm what loan product it belongs to and how long that pricing lasts.
This is one of the easiest mistakes to make. A borrower sees an attractive rate and assumes that will be the cost of the loan for the next 10, 15, or 20 years. In practice, many housing loans have an initial fixed period, then shift to a repricing structure.
So the first thing to ask PNB is simple: Is this fixed, variable, or fixed only for a limited term?
A short fixed period may start lower, which helps with early affordability. But once that period ends, the rate can be adjusted based on the bank’s repricing rules and market benchmarks. A longer fixed period usually gives more payment stability, though it may begin at a higher rate.
Neither structure is automatically better. It depends on how much payment uncertainty you can handle.
If your monthly budget is already tight, a longer fixed period may be easier to live with because the dues are more predictable. If you expect to refinance, prepay, or sell the property within a few years, a shorter fixed period may still work, provided you understand the risks.
Ask for these details in writing:
That information matters more than the headline number by itself.
Even within the same loan program, your final offer may depend on how strong your application looks on paper. Banks are not only evaluating the property. They are evaluating your capacity to repay over a long period.
Stable income usually helps. Salaried borrowers with complete employment records often move through review more smoothly because their earnings are easier to verify. Self-employed applicants can still qualify, but the bank may take a closer look at business documents, cash flow consistency, and tax records.
Credit history also matters. If your record shows clean repayment behavior and manageable existing debt, your application generally looks stronger. If you already carry heavy monthly obligations, the bank may see less room in your budget for a new mortgage.
Property details can influence pricing too. A standard residential home in an acceptable area is different from a specialized property or one with documentation issues. The cleaner the file, the easier it is for the lender to assess risk.
To improve your chances of a better offer, focus on basics that are actually within your control:
None of this guarantees a specific rate, but it reduces friction and helps the bank evaluate you more confidently.
When you compare PNB home loan offers, the goal is not to find the lowest visible rate. The goal is to find the option that produces a payment you can sustain and a total cost you can accept.
Start with a simple loan comparison sheet. Put the offers side by side and review:
This keeps you from overvaluing a low starting rate while ignoring the parts that make a loan expensive later.
Loan term matters more than many borrowers expect. A longer repayment period can reduce monthly dues, which helps cash flow. But it also usually increases the total interest paid over time. A shorter term often raises the monthly payment but can lower the lifetime borrowing cost.
That is why it helps to run at least three scenarios in a mortgage calculator: a comfortable term, a shorter term, and a stressed scenario where rates rise after repricing. If one option only works when everything stays perfect, it is probably too aggressive.
Look at annual and total loan cost, not just the opening rate. Small differences compound over years. That is where the real comparison happens.
Borrowers often spend hours comparing rates and then treat fees as minor details. That is a mistake. A loan that looks competitive on interest can become less attractive once charges are added in.
With a mortgage, extra costs may include processing fees, appraisal charges, insurance, notarization, and other administrative expenses. Some are one-time costs at the start. Others may recur during the loan life. If you do not ask for a full estimate early, the total budget can feel much heavier than expected.
This is especially important if you are stretching for down payment, moving costs, and emergency savings at the same time. Even when the monthly installment seems manageable, upfront charges can create cash pressure.
Ask PNB for a full loan estimate that shows both recurring and non-recurring costs. Then check:
If you expect to refinance later, prepayment terms matter. A loan with a decent rate but expensive exit charges can limit your flexibility.
The practical move is boring but effective: total everything. Add interest, fees, and known charges across the repayment horizon you realistically expect to keep the loan. That gives you a truer number than the advertised rate alone.
A mortgage calculator is not just for curiosity. It is one of the quickest ways to test whether a PNB mortgage offer makes sense before you start collecting documents.
Begin with the basics: property price, down payment, loan amount, interest rate, and term. That gives you an estimated monthly amortization. Then change one variable at a time.
Useful tests include:
This exercise does two things. First, it shows whether the payment still works if rates move later. Second, it helps you avoid borrowing right up to the edge of what you can technically qualify for.
An affordability calculator is helpful here too. Approval and comfort are not the same thing. A bank may approve a loan amount that still leaves your monthly budget too tight once utilities, association dues, maintenance, school costs, and emergencies are included.
It also helps to prepare a document checklist early. Income proof, IDs, tax records, and property documents tend to cause delays when gathered too late. A cleaner application does not just reduce stress. It gives you a better shot at getting a clear and timely loan assessment.
Run the numbers first. It is easier to adjust the plan before application than after you are emotionally committed to a property.
If you are down to actual options, keep the decision framework simple.
Choose based on budget stability first. If you need predictable payments, favor a structure with a fixed period that gives you enough breathing room. If your income is variable, do not assume future rate increases will be easy to absorb.
Then check total cost. Compare the monthly payment against the full borrowing cost over the period you expect to hold the loan. A slightly higher monthly amount may be worth it if it saves substantial interest later. Sometimes it is not.
Next, review flexibility. If there is a good chance you will prepay, refinance, or sell, look closely at penalty clauses and repricing rules. A cheap entry rate can be less useful if it locks you into expensive exit terms.
Finally, pressure-test the paperwork. Make sure your income documents are complete and your property file is in order. Questions about employment, unclear business income, or missing property records can slow approval and affect how smooth the process feels from start to finish.
The best loan is rarely the one with the flashiest promo. It is the one you understand clearly, can afford under normal and slightly worse conditions, and can keep without damaging the rest of your finances. If you are also comparing offers from other lenders, reviewing PNC mortgage loan options can help frame the differences in structure and next steps.
No. Rates can vary based on the loan program, your income profile, credit standing, property details, and the repayment term you choose.
Not really. You also need to check fees, fixed-period length, repricing rules, and total repayment cost. A low starting rate can become expensive later.
Yes. Use a mortgage calculator to estimate monthly dues under different rates and loan terms before applying.
Because even a small difference in interest can change both your monthly payment and the total interest paid over many years.
Incomplete income documents, unclear employment or business records, and missing property papers are common reasons.
Yes. Processing, appraisal, insurance, and related charges can materially raise the full cost of the mortgage, even when the rate looks competitive.



