








Newsletter Subscribe
Enter your email address below and subscribe to our newsletter

Enter your email address below and subscribe to our newsletter
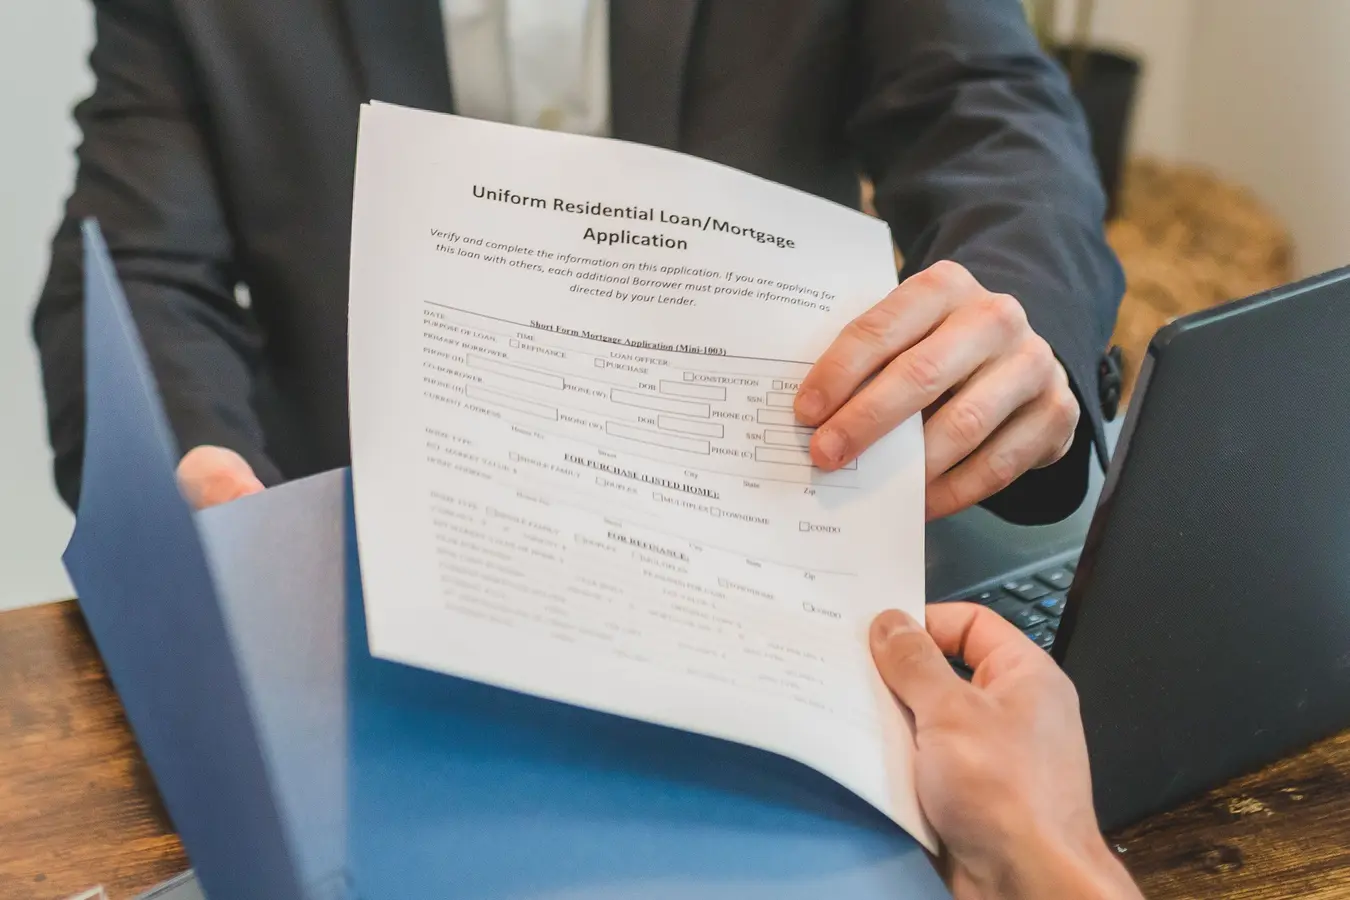
You see the phrase business mortgage loan on a lender site, in a broker email, or while looking at a property your company wants to buy. It sounds familiar, but not quite. Is it just a mortgage for a business? Is it based on the building, your revenue, or both? And if you already rent space, is buying even what the lender means?
That confusion is common because commercial borrowing uses some of the same language as home lending, while working very differently in practice. A business mortgage loan usually sits somewhere between a property deal and a business finance decision. The property matters, but so do your accounts, deposit, cash flow, and plans for the building.
If you want the plain-English version before comparing rates or talking to lenders, start here. This guide explains what the term usually means, who it is for, what it can fund, how repayment tends to work, and where people most often mix it up with other types of borrowing.
In most cases, a business mortgage loan means a loan used by a business to buy or refinance commercial property, with that property acting as security for the lender.
That is the core meaning. The business might be buying an office, warehouse, shop, clinic, workshop, mixed-use unit, or another building connected to commercial activity. Sometimes the property is where the business trades. Sometimes it is held as an investment and rented out.
The reason the term confuses people is that it is not just about the property. Lenders also want to know whether the business can afford the repayments, how stable the income is, how much deposit is available, and whether the property itself is acceptable security.
So if you are asking what a business mortgage loan means, the practical answer is this: it is a property-backed loan for business or commercial real estate, assessed using both the asset and the financial strength behind it.
That is different from a general business loan used for stock, marketing, payroll, or working capital. A commercial mortgage is tied mainly to property. The property sits at the center of the deal.
A business mortgage is not only for large companies. Sole traders, partnerships, limited companies, and established small businesses may all use one, depending on the lender’s rules.
A common example is a business owner who is tired of paying rent on premises they have occupied for years. Buying the unit can offer more control over costs, more stability, and in some cases a long-term asset on the balance sheet.
Another example is expansion. A company outgrows its current space and needs a larger warehouse, more office room, or a better retail location. A business mortgage can fund that move if the numbers stack up.
There are also borrowers who use this type of loan for investment purposes. They may buy commercial property through a company and let it to tenants. In that case, the lender still looks at the property and the borrower, but rental income becomes a bigger part of the assessment.
That is why the same phrase can describe slightly different situations. The loan structure may look broadly similar, but the underwriting changes depending on whether the property will be occupied by your own business or held as an investment.
People often assume it only applies to a straightforward purchase, but a business mortgage loan can be used in a few practical ways.
The exact use depends on the lender and the risk profile. Some are comfortable with a broad range of property types. Others prefer standard assets that are easier to value and resell.
This is also where many borrowers confuse a commercial mortgage vs business loan. If the main purpose is to buy or refinance property, you are usually in commercial mortgage territory. If the money is needed for everyday trading, hiring, tax, stock, or equipment, that may point to a different product even if your business is strong enough to borrow.
Knowing the intended use upfront saves time. It helps you speak to the right lenders, gather the right documents, and avoid applying for finance that was never designed for the job.
Approval is rarely based on one factor. Lenders tend to assess the deal from a few angles at once.
First is the property itself. They will look at value, condition, location, use, and how easy it would be to sell if things went wrong. A standard office or warehouse may be simpler to finance than a highly specialised site.
Second is your contribution. In many cases you will need a deposit, and the size of that deposit affects both risk and pricing. A stronger deposit usually gives the lender more comfort.
Third is the business profile. Expect questions around trading history, turnover, profit, debt levels, existing commitments, and recent accounts. Bank statements are often reviewed alongside filed financials to see how the business performs in real conditions, not just on paper.
Credit matters too. That can include the business credit profile, and often the directors or owners behind it, especially in smaller firms.
If you want a quick diagnostic before applying, look at four things: deposit size, cash flow, trading history, and property type. Those are usually the pressure points.
A loan eligibility checker can be useful at this stage, but it is only a first filter. For a more serious application, a lender checklist and a realistic repayment schedule will tell you much more about whether the deal is actually workable.
The word mortgage makes people assume the process will feel familiar. It usually does not.
A residential mortgage is mainly designed around personal income and a home. A business mortgage is built around commercial property and business risk. That means lenders often ask different questions, apply different affordability logic, and price loans differently.
Business mortgage rates are often higher than residential rates. Not always dramatically, but commercial lending is usually seen as more complex and sometimes riskier. The lender may be dealing with variable business income, niche property types, or buildings that are harder to sell than houses.
The term length, fees, valuation process, and legal work can also be different. Some loans are arranged with fixed rates, others variable, and the lowest headline rate does not always mean the lowest total cost once fees and conditions are included.
If you are comparing options, a commercial mortgage calculator is useful for monthly estimates, but do not stop there. Test the full borrowing cost across the term, including arrangement fees, valuation fees, legal fees, and any early repayment charges. Small differences in rate can matter, but so can the structure wrapped around them.
One of the most important distinctions is whether the business will use the property itself or rent it out.
With owner-occupied commercial property, your company trades from the building. Think of a manufacturer buying its own unit or a firm purchasing the office it currently leases. In that case, the lender will focus heavily on business affordability because your operations are expected to support the repayments.
With investment commercial property, the building is mainly there to generate rental income. The lender still looks at the borrower, but the tenancy profile, lease terms, expected rent, and tenant quality become more important.
This matters because pricing, deposit requirements, and loan structure can shift between the two. The same property may even be viewed differently depending on how it will be used.
Borrowers sometimes gloss over this when making early enquiries. That creates confusion later. Be clear from the start: will the business occupy the building, partly occupy it, or hold it as an investment? A simple use-case worksheet can help you map that out before speaking to lenders or brokers.
Most business mortgage loans are repaid over an agreed term through monthly payments, though the structure can vary. Some are capital-and-interest, where you gradually repay the loan balance. Others may include an interest-only period, depending on the deal and the lender’s appetite.
What matters is not just whether you can meet the first repayment, but whether the structure still makes sense if trading softens, interest rates move, or a planned expansion takes longer than expected.
Before signing, check these points carefully:
A repayment schedule template is especially useful here. It turns an abstract loan into a timeline you can test against real business cash flow.
That is really what the phrase comes down to in practice. A business mortgage loan means property-backed borrowing for commercial purposes, but the smart decision is not understanding the definition alone. It is understanding how that definition plays out in your accounts, your premises, and your risk.
It usually means a loan used by a business to buy or refinance commercial property, with the property used as security.
No. A business mortgage is for commercial property and is assessed using business finances, risk, and property type rather than just personal income.
Depending on the lender, applicants can include companies, sole traders, partnerships, and commercial property investors.
Most commonly, it is used to buy or refinance offices, shops, warehouses, and other commercial premises.
Usually yes. The amount varies, but lenders often expect the borrower to contribute part of the purchase price.
A commercial mortgage is mainly for property and is secured on that property. A business loan can be used for wider business needs such as cash flow, stock, or expansion.
They usually review your deposit, accounts, bank statements, credit profile, trading history, and the property being financed.
Yes. Lenders often assess owner-occupied and investment commercial property differently, including how they price the loan and judge affordability.



